Value Is Not CreatedWhen You Sign the Deal
- Home
- Human Resources
- Value Is Not CreatedWhen You Sign the Deal
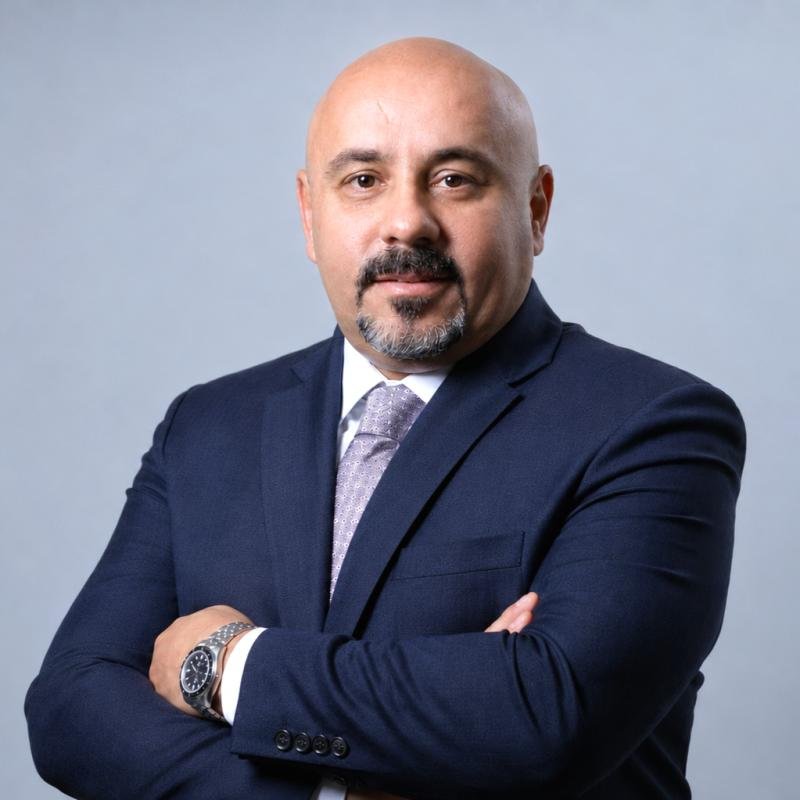
Bacem Jarraya on acquisitions, IPO readiness, international growth and the future of finance
Bacem Jarraya
Chief Financial Officer, Alkhorayef Petroleum Company
The best financial insight does not tell the board what decision to make. It makes the return, risk, cash impact and trade-offs clear.
In this Finance Leadership conversation, Hani Lakhani examines how organizations can pursue ambitious growth without weakening financial discipline. Drawing on his experience at NEOM, he discusses the signals that reveal emerging opportunities, why transformation must change decision-making rather than merely digitize existing processes, and how AI can move finance from producing numbers to shaping strategic choices.
1. What separates a successful acquisition from one that fails to create the expected value?
For me, the difference is rarely the transaction itself. It is what happens before and, even more importantly, after the deal closes. You can have a very strong strategic rationale and a valuation that looks attractive on paper, but if you underestimate integration, culture, people or execution, value can disappear very quickly. The financial model is important, but it is still a model. The real test is whether the assumptions behind it can actually be delivered. I also believe companies sometimes spend too much energy negotiating the last few points of the purchase price and not enough time preparing for Day 1 and the first 100 days. Who are the key people we need to retain? Where exactly will the synergies come from? How quickly can we integrate systems, controls and reporting? What could disrupt customers or operations? A successful acquisition is one where the strategic logic, the price paid and the integration plan all work together. Ultimately, value is not created when you sign the deal. It is created when you deliver what you said the deal would deliver.
2. What are the biggest financial considerations companies should address before preparing for an IPO?
An IPO puts a company under a completely different level of scrutiny. It is not simply about producing audited financial statements or achieving a certain valuation. The organization has to be ready to operate as a public company. From a finance perspective, I would focus first on the quality and predictability of earnings and cash flow. Investors will want to understand not only how much profit you generate, but how sustainable it is, how well it converts into cash and what is driving the growth. The second area is the quality of the finance organization itself: reporting, internal controls, governance, tax, treasury, systems and the ability to close and communicate results accurately and consistently. You need to identify weaknesses before the market identifies them for you. The third consideration is the equity story. Management needs to explain, in a very simple way, where the company is today, where the growth will come from and how capital will be allocated. I often say that IPO readiness is not a finance project. It is a transformation of the entire organization. Finance may be at the centre of it, but the whole business needs to develop the discipline and transparency expected from a listed company.
3. What are some of the biggest financial risks companies expanding across multiple regions tend to overlook?
One of the biggest mistakes is assuming that a successful business model can simply be replicated from one country to another. Every market brings a different combination of tax, foreign exchange, regulation, banking, working capital and geopolitical risk. Individually, each issue may look manageable. The challenge arises when several of them occur at the same time. THE LEADERSHIP GAZETTE | FINANCE LEADERSHIP FINANCE LEADERSHIP • 3 Working capital is particularly important. A business can be profitable on paper and still destroy cash if receivables increase, inventory builds up or cash becomes trapped in a country. Currency exposure is another area that is often underestimated, especially when revenues and costs are in different currencies. Tax and regulatory changes can also have a significant impact on the economics of an investment after the original decision has been made. For me, international growth needs to be assessed through both a P&L lens and a cash-and-risk lens. Revenue growth is attractive, but the real question is: how much sustainable cash and return are we generating after considering all the risks we are taking?
4. What opportunities do you see for AI to transform finance and business decision-making?
I think AI will fundamentally change finance, but probably not by replacing the CFO or the finance team. It will change where we spend our time. A significant amount of finance work is still spent collecting information, reconciling data, preparing reports and explaining what has already happened. AI gives us the opportunity to automate much of that work and move finance closer to real-time decision-making. Imagine a CFO being able to ask: Why did margins decline this month? Which customers are driving the increase in working capital? Where are we likely to miss the forecast? What happens to cash flow if oil prices, foreign exchange or interest rates move?—and receiving meaningful analysis almost immediately. That changes the role of finance from reporting the past to helping the business anticipate the future. But I would add one important point: AI does not remove the need for judgement. If anything, judgement becomes more important. AI can process enormous amounts of information, identify patterns and challenge assumptions, but management still has to understand the business context, assess risk and make the decision. I see the future CFO as combining three things: financial discipline, business judgement and technology.
5. As a board member, what financial insights do you believe are most valuable when evaluating strategic decisions?
At board level, I don’t think the most useful finance presentation is the one with the most numbers. It is the one that makes the decision clearer. When evaluating a strategic investment, acquisition or expansion, I want to understand a few fundamental things: What return are we expecting? How much cash are we putting at risk? What assumptions have to be true for the investment to succeed? What happens if those assumptions are wrong? And what alternatives do we have? I also pay close attention to cash generation and the balance sheet. EBITDA and net income are important, but neither pays the debt nor funds the next investment. Cash does. The CFO’s responsibility at board level is also to bring balance to the discussion. We should support growth and not become the person who always says “no,” but we also need to challenge optimism when necessary. For me, the best financial insight does not tell the board what decision to make. It gives the board enough clarity to understand the return, risk, cash impact and trade-offs behind the decision. That is ultimately where finance adds the most value: not just explaining the numbers, but helping people make better decisions.
Stay Ahead
Get exclusive interviews & award updates in your inbox
A global business magazine bringing you exclusive interviews, in-depth features, and stories on the leaders shaping industries worldwide.
Quick Links
© 2026 The Leadership Gazette