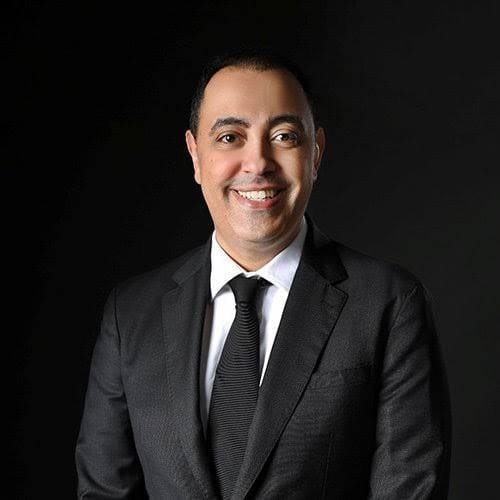
Mohamed Aboubakr
Group CFO | Finance Strategy Transformation and Value Creation
The Group CFO of Albawardi Group Holding explains how finance leaders should test investment opportunities, guard against over-optimism in acquisitions and prepare businesses for the demands of a public listing.
Investment decisions are rarely determined by a single ratio. For Mohamed Aboubakr, Group CFO of Albawardi Group Holding, the strongest opportunities are those that combine market relevance, strategic and cultural alignment, credible returns, liquidity discipline and an executable operating plan. In this interview, he discusses the finance test for investments, the danger of optimism in mergers and acquisitions, the strategic value of defensive deals and the financial foundations required before an IPO.
1 . What makes an investment opportunity worth pursuing from a finance perspective
Industry and market viability
The first question is whether the investment operates in the right sector. Does it solve an existing market need, or one that is reasonably certain to emerge? More importantly, is the industry likely to endure in a form that allows the investment to create value over the long term?
Strategic and cultural fit
Financial returns
Liquidity and cash-flow timing
Execution and operational capacity
The opportunity must also match the organisation’s risk appetite and execution capability. If it involves specialist knowledge, a new geography or an unfamiliar segment, the company needs a credible plan to retain talent, allocate responsibilities and coordinate with its partners. It must also have enough management capacity to pursue the opportunity without weakening its core operations or losing existing business momentum.
2 . What is the biggest financial challenge during an M and A transaction
Challenges can include overvaluation, cash-flow misalignment, hidden liabilities and the failure to realise expected synergies. In my view, however, the greatest danger is allowing over-optimism to weaken an otherwise prudent assessment.
An acquisition requires a significant commitment of capital. It is dangerous to assume that the valuation is unquestionably correct, every synergy will materialise, integration will proceed smoothly and no unexpected liability will emerge. That combination of assumptions can place the buyer in a difficult position unnecessarily.
Finance leaders should stress-test the valuation, model a range of scenarios and create a meaningful cushion for surprises. The integration learning curve can be expensive and slower than anticipated, particularly when the buyer has limited experience in the target’s industry. The less familiar or more volatile the sector, the greater the risk allowance should be.
It is also prudent to allocate a specific reserve for unforeseen costs and ensure that uncertainty is reflected in the purchase consideration. Positive surprises are always welcome, but they should never be required for the original investment case to work.
3. How do you evaluate whether an acquisition will create long term value
Assessing long-term value goes beyond conventional quantitative measures. Return on invested capital, run-rate synergies, cost savings and scalability are important, but the evaluation must begin with the strategic intent of the transaction. Why are we acquiring this business?
An acquisition creates lasting value when it advances a defined strategic objective, such as entering a new market, acquiring intellectual property or specialised know-how, securing market share, or mitigating a critical downside risk. The analysis should remain multidimensional even when one strategic consideration is particularly important.
Value creation is not always additive; it can also be defensive. In the telecommunications sector, I witnessed the acquisition of an internet gateway provider in a market served by only two gateway operators. A major competitor had already acquired the first operator. If it had also been allowed to acquire the second, our company would have faced an existential vulnerability because a rival could have controlled the essential infrastructure on which the business depended.
In that context, paying a three-times premium to the conventional valuation was justified. The transaction protected the core business model and preserved operational autonomy. Its real value was not simply incremental earnings; it was the protection of the company’s market position and long-term strategic independence. Value must therefore be measured against the specific objective the transaction is designed to achieve.
4. What key financial factors should a company consider before an IPO
An IPO can be a powerful value-creation milestone. It can strengthen business sustainability, improve governance, raise growth capital and create an exit route for investors at an attractive valuation. The outcome may be compelling, but the journey is complex and demands substantial preparation.
The first consideration is the strength of financial reporting. Can the company complete its monthly, quarterly and annual close within demanding deadlines? Does its ERP environment support detailed analysis and the disclosure requirements of applicable standards such as IFRS? Does the finance team have the required technical capability and understand the regulatory language of the Capital Market Authority?
Auditor readiness is equally important. The audit firm must have the necessary regulatory licence, market credibility and capacity to meet tight interim and year-end reporting deadlines.
The company must also test the quality and sustainability of its financial performance. Are profits recurring, or are they supported by one-off gains? Do measures such as EBITDA support a credible valuation that can withstand investor and regulatory scrutiny?
Operational and financial independence
Business model and regulatory fit
Listing route and market choice
Execution roadmap and contingency planning
Stay Ahead
Get exclusive interviews & award updates in your inbox
A global business magazine bringing you exclusive interviews, in-depth features, and stories on the leaders shaping industries worldwide.
Quick Links
© 2026 The Leadership Gazette