Finance as the Engine of Strategic Capital Allocation

Zaher Husami on liquidity, project finance and building investment-ready organisations

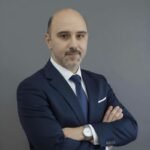
Zaher Husami

Vice President of Treasury and Investments | Zahran Holdings

Published on Nov 4, 2026

With experience spanning treasury, investments, strategic finance, project finance and IPO readiness, Zaher Husami brings a holistic view of how capital should be protected and deployed. In this conversation with The Leadership Gazette, he discusses the evolution of finance into a decision-making engine, the balance between liquidity and growth, the growing complexity of treasury in Saudi Arabia and what makes a company genuinely investment-ready.

1 . You have worked across treasury, investment and strategic finance. How has your view of the finance function changed as you moved into more senior leadership roles?

Earlier in my career, I viewed finance largely through the lens of numbers, controls, liquidity and risk management. As I moved into more senior roles across treasury, investment and strategic finance, my perspective changed significantly.

Today, I see finance as a business partner and, more importantly, as part of the organisation’s decision-making engine. The role is not simply to report what happened financially, but to help management understand what could happen next and make better decisions around capital, liquidity, risk and growth.

In a diversified group, this becomes even more important. Treasury decisions can directly affect investment capacity, financing costs and the ability to pursue new opportunities. I therefore try to look at the organisation from a holistic capital-allocation perspective rather than treating treasury, investments and corporate finance as separate functions.

At the senior level, I believe the real value of a finance leader is the ability to balance financial discipline with commercial ambition—protecting the company today while creating the financial flexibility to capture opportunities tomorrow.

2. When a company is pursuing aggressive growth, how do you decide how much liquidity to preserve and how much capital to deploy into new opportunities?

For me, liquidity is not simply about keeping cash in the bank. It is about maintaining enough financial flexibility to protect the business while having the confidence to deploy capital when the right opportunity emerges.

I normally assess liquidity through several dimensions: the operating needs of the group, upcoming debt maturities and commitments, access to undrawn facilities, the cost and availability of external financing, and the quality of the investment opportunities available to us.

Liquidity should also be dynamic. Holding excessive idle cash has an opportunity cost, while deploying too much capital can leave the business vulnerable when market conditions change.

The key is to establish a clear liquidity buffer and then define how much capital can be deployed beyond that level without compromising the group’s resilience. Once that framework is in place, investment decisions become much more disciplined. The objective is not to maximise cash or maximise investment, but to optimise the balance between security, return and strategic flexibility.

3. What are the biggest treasury challenges facing Saudi businesses as they become more involved in large-scale projects and international markets?

One of the biggest challenges is that treasury is becoming much more complex. Saudi businesses increasingly operate across multiple entities, currencies, jurisdictions and financing structures while participating in projects that require significant capital over long periods.

This creates a need for more sophisticated liquidity planning, interest-rate and currency-risk management, working-capital optimisation and banking diversification.

Another challenge is the speed of growth. Sometimes a business expands faster than the treasury infrastructure supporting it. An organisation may have strong operations and a strong balance sheet, but if cash visibility, forecasting, funding lines and risk controls do not evolve at the same pace, it can face unnecessary financial pressure.

International expansion adds another layer. Companies need to understand not only the financing available to them, but also the regulatory, currency, tax and cross-border considerations associated with different markets.

Saudi treasury functions are moving from being primarily transactional to becoming much more strategic. The next step is building treasury platforms that give management real-time visibility and allow capital to be allocated efficiently across the group.

4. You have significant experience in project finance. Which financial risks do companies most often underestimate when financing large, long-term projects?

One of the biggest risks companies underestimate is the difference between the financial model and the reality of execution.

A project may look very attractive on paper, but relatively small changes in construction costs, delays, interest rates, working-capital requirements or the timing of cash flows can significantly affect returns and debt-servicing capacity over a long period.

Refinancing risk is also frequently underestimated. When a project has a long economic life but its financing has a much shorter maturity, management must look beyond the initial financing and consider what happens when the debt needs to be refinanced under potentially very different market conditions.

I also pay close attention to the quality of the assumptions behind the model. Revenue projections, cost escalation, utilisation, working capital and exit assumptions need to be stress-tested rather than simply accepted as base-case forecasts.

Successful project finance is not just about securing funding at an attractive cost. It is about ensuring that the project’s cash flows, financing structure and risk profile remain resilient under different scenarios. The strongest structures can withstand a reasonable degree of uncertainty without placing the broader business under financial pressure.

5. How do you approach banking relationships strategically rather than simply treating banks as sources of funding?

I have always believed that a good banking relationship should go well beyond borrowing money.

Banks can provide much more value through market intelligence, structuring expertise, investment opportunities, transaction banking, risk management and access to international markets. The strongest relationships are those in which both sides understand the client’s long-term strategy rather than focusing only on the next financing requirement.

I also believe in creating healthy competition among banking partners. Different banks have different strengths, whether in corporate lending, capital markets, wealth management, trade finance or international investment opportunities. The treasury function must understand those capabilities and build the right banking ecosystem around the business.

At the same time, relationships have to be built on credibility. Banks need to know that when you make a commitment, you will deliver. Transparency, consistency and good communication become particularly important during challenging market conditions.

The objective is not to have the largest number of banks. It is to have the right banking partners, with the right capabilities, aligned with the company’s strategic direction.

6. From your experience with investments and IPOs, what makes a company genuinely investment-ready beyond having strong financial statements?

Strong financial statements are only the starting point.

An investment-ready company needs a clear strategy, strong governance, reliable financial information and, importantly, a management team that can articulate where the business is going and how capital will create value.

Investors also look beyond historical performance. They want to understand the quality and sustainability of earnings, cash-flow generation, capital requirements, the company’s competitive position and the key risks that could affect future performance.

From a treasury and investment perspective, I would also examine the company’s capital structure, liquidity position, debt profile, banking relationships and ability to withstand different market scenarios.

There is also a cultural element that is sometimes underestimated. Investment readiness requires transparency and discipline. Management needs to be comfortable with greater scrutiny, stronger governance and difficult questions about the business.

Ultimately, an investment-ready company is one where the numbers, strategy, governance and management narrative all tell the same story. That alignment is what gives investors confidence.
Stay Updated with TLG

Get the latest interviews, leadership insights and award updates, delivered to your inbox.